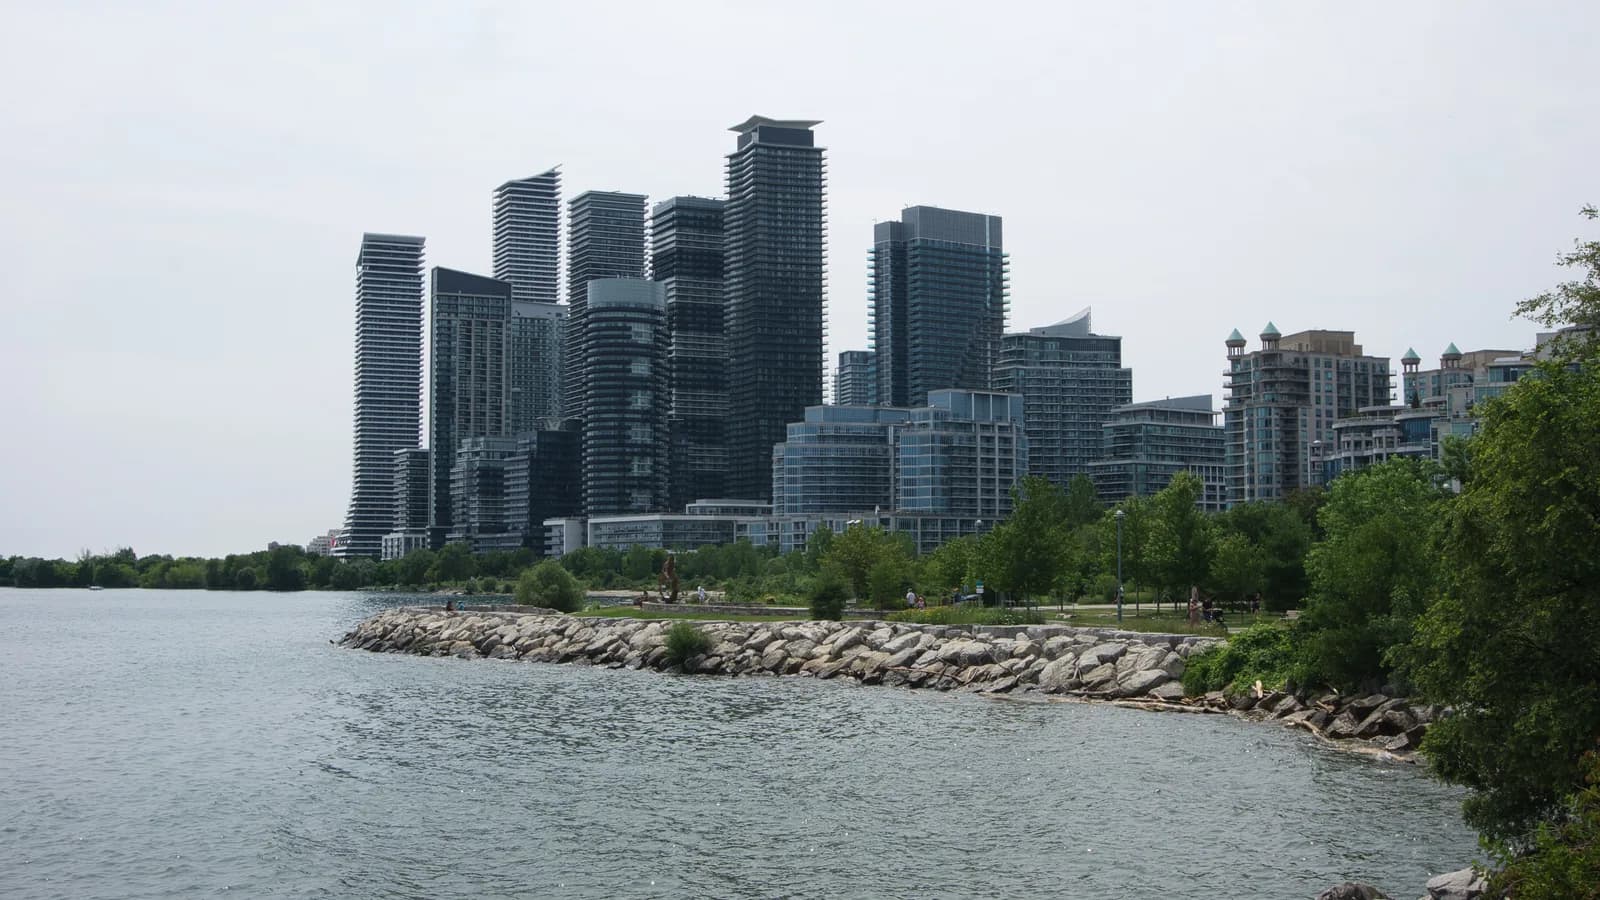
From the rocks at Humber Bay, the glass towers along Toronto's western waterfront look finished and quiet. The latest industry count of new condominium sales across the wider region says much of the recent activity is happening inside buildings that are already complete, and that a large share of those sales went to investment groups buying in bulk.
Urbanation, a Toronto condominium research firm, released its third-quarter 2026 condominium market survey on 19 October. It counted 760 new condominium apartment sales in the Greater Toronto Hamilton Area (GTHA) in the quarter, double the total a year earlier and the second quarterly rise in a row. Even so, Urbanation puts the quarter 78% below its latest 10-year average for third quarters. Sales over the past two quarters totalled 1,531 units, roughly matching the 1,578 units sold in all of 2025. Urbanation is an industry data source, not a public statistical agency, and the figures below are attributed to its survey.
Of those 760 sales, investment groups bought 339 units in bulk transactions, which Urbanation puts at 45% of all new-condo sales. Sales in completed buildings reached 648 units, 85% of the total. Urbanation describes both the completed-building total and that share as records. Pre-construction sales moved the other way, falling 61% from a year earlier to 60 units, the 12th consecutive quarter of annual decline on Urbanation's series. Those bulk findings are set out in more detail in our 22 October brief. This piece sets the same Urbanation survey beside the latest Toronto Regional Real Estate Board resale figures.
That clearance of finished stock has started to show in the inventory count. Completed and unsold units fell 7% from 5,485 in the second quarter to 5,127 in the third, the first quarterly decline in four years on Urbanation's figures. The backlog is still large by recent standards. Urbanation says it is 40% higher than a year ago and four times the 1,279 units recorded two years ago.
The price lines show where bulk buyers stepped in. Bulk sales averaged C$763 per square foot, which Urbanation calculates as an average discount of 40% to the original selling prices in the same buildings. Developers were asking an average of C$1,157 per square foot for completed and unsold units, 4% lower than a year earlier and 20% below the peak of C$1,446 in the second quarter of 2023. New units sold outside bulk and luxury deals averaged C$1,045 per square foot.
Urbanation's own resale series for the GTHA also shows a quieter quarter. Sales, listings and average prices per square foot all fell from a year earlier, with smaller declines in the former City of Toronto than in the outer 416 and 905 areas. The fuller Urbanation resale lines are in that 22 October brief.
A separate reading of the resale market comes from the Toronto Regional Real Estate Board (TRREB), which publishes Multiple Listing Service (MLS) figures for what it calls the Greater Toronto Area (GTA). That board area is not the same geography as Urbanation's GTHA. TRREB's GTA covers the City of Toronto, the regions of Halton, Peel, York and Durham, Orangeville in Dufferin County, and five municipalities in south Simcoe County. As of 28 October 2026, TRREB's latest Market Watch is still September 2026, released on 6 October.
In September, TRREB recorded 1,316 condo apartment sales across its area, 7.8% fewer than in September 2025. The average selling price was C$605,257, down 7.7%. The City of Toronto accounted for 884 of those sales, down 5.5%, at an average of C$640,248, down 6.1%. New listings of condo apartments totalled 4,523 across the TRREB area, and 8,226 were active at month end.
TRREB's MLS Home Price Index (HPI) apartment benchmark for all TRREB areas was C$527,200 in September, 6.7% lower than a year earlier. In the City of Toronto the apartment benchmark was C$543,800, down 6.4%. A benchmark price is the modelled price of a typical home with a fixed set of features, so it follows price movement without being pulled around by changes in which homes happened to sell that month. Across all home types, TRREB's composite benchmark was C$917,600, down 4.7%, and overall GTA sales were 5,040, down 9.0%.
On the new-build supply side, Urbanation counted construction starts on only 381 units in a single project in the third quarter, bringing starts for the first three quarters of 2026 to 2,696 units, 82% below its 10-year average for the same period. Units under construction fell 38% from a year earlier to 35,920, the lowest level since early 2012 on its series, and 7,685 of those remain unsold. Completions in the quarter were 2,578 units. Urbanation's schedule of completions runs to 20,868 units for full-year 2026, then 15,825 in 2027, 12,065 in 2028 and 4,213 in 2029.
Sources
Sources read 28 October 2026.
- GTHA New Condo Sales Double from a Year Ago in Q3, Urbanation Inc., 19 October 2026.
- Economic Uncertainty Kept GTA Homebuyers on the Sidelines in September, Toronto Regional Real Estate Board news release, 6 October 2026.
- Market Watch, Toronto Regional Real Estate Board, September 2026.
- Market Watch, Toronto Regional Real Estate Board (index page confirming September 2026 as the latest report as of 28 October 2026).
- MLS Home Price Index, Canadian Real Estate Association (benchmark definition).